While there are many folk (often with dubious motivation) who claim that Renewable Energy Sources can never supply all a nations electricity needs, there is also a rather more sensible discussion on the role of nuclear power in the operation of our grids.
The thinking is that nuclear provides a robust, ‘firm’ (i.e. predictable and available) electricity supply that ensures that the baseload is covered. This is needed because renewables are intermittent.
Intermittency and capacity factors
Modern UK renewables perform far better than the existing long‑term fleet averages suggest: new offshore wind farms typically achieve 45–55% capacity factors (the real-world operational output vs. the nameplate or maximum output), a consequence of taller towers, larger rotors and steadier North Sea winds; new onshore wind sites reach around 30–40%. It’s older turbines that make the national average appear lower. Solar farms in the UK are roughly 11–12% capacity factor, limited mainly by latitude rather than technology.
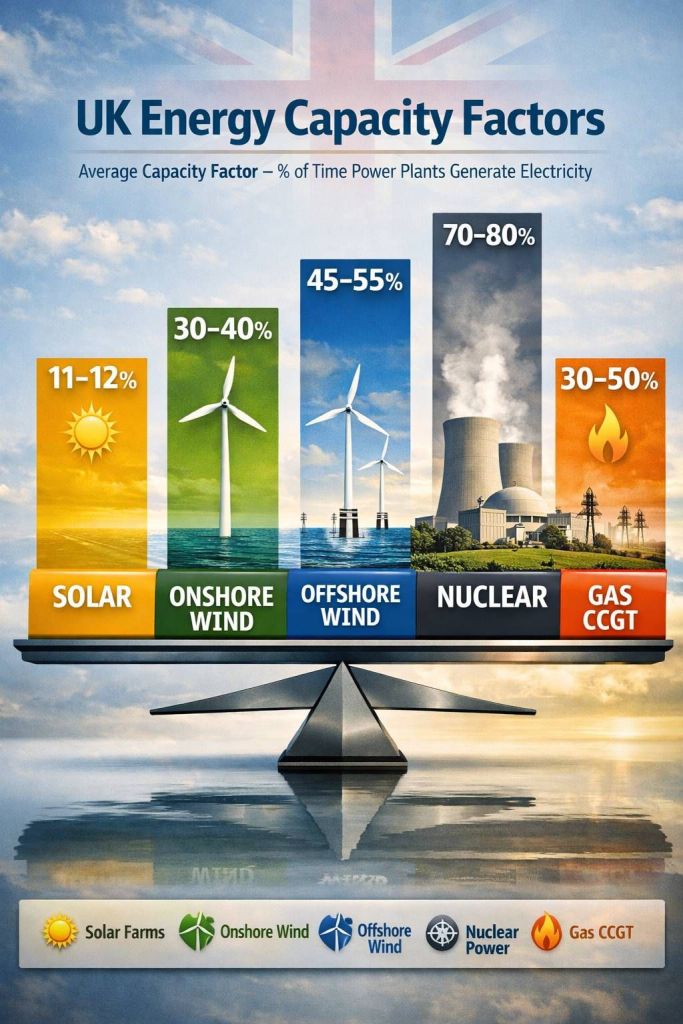
To add perspective, nuclear usually runs at 70–80%, shaped by long maintenance outages but high reliability when online, while gas CCGT stations operate at about 30–50% in practice, not because they cannot run harder but because they increasingly serve as mid‑merit and peaker plant in a renewables‑led system.
To address the intermittency issue the suggestion is that we need more nuclear in order to eliminate gas and so achieve a zero carbon emissions grid. It’s more than a suggestion, as literally billions of pounds are being invested in nuclear plants. Is this a wise investment?
Do we need nuclear power?
Let’s explore the topic in more detail. The following isn’t definitive, none of the team here are nuclear energy engineers, but we are well informed and we have given it our best shot at the analysis.
There is a credible case that, in the next 10–20 years, countries with strong renewable resources are unlikely to need new grid‑connected nuclear. Renewables + storage + demand flexibility are scaling faster, are cheaper, and are more predictable than nuclear can be deployed. Nuclear may still play a role in some regions, but it need not be a system necessity in the medium term.
Looking ahead
By 2040–2045, most grids can reach 80–95% decarbonisation using RES, storage, interconnection, and demand‑side management alone.
Nuclear is only “needed” in systems that lack good renewable resources, have weak grids, or have political reasons to prefer it.
Renewable scaling is outpacing every forecast
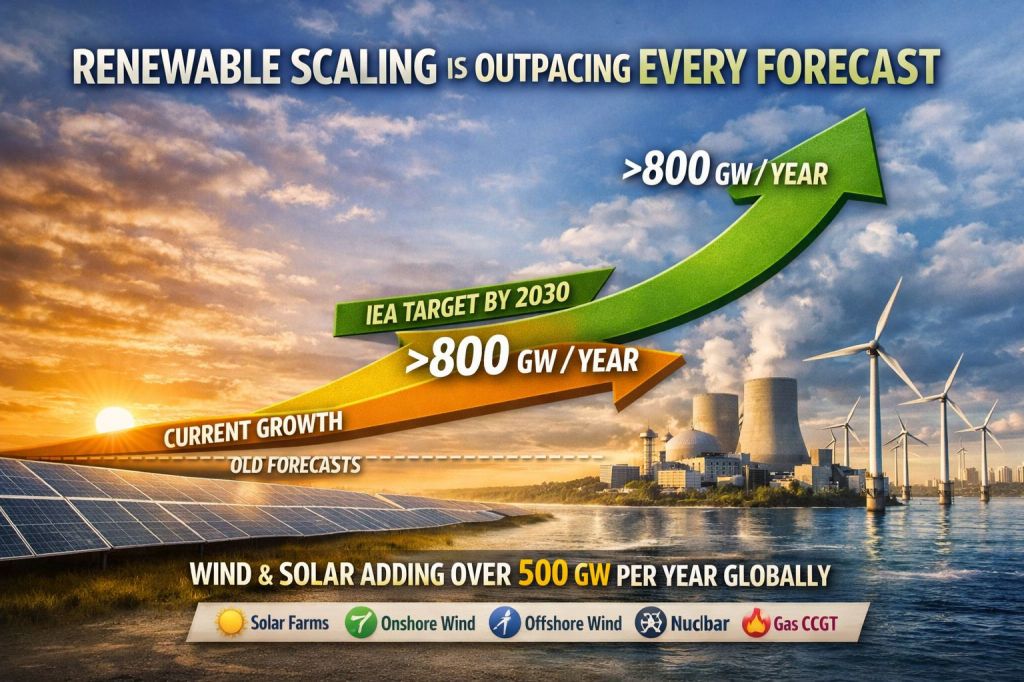
Wind and solar are now adding >500 GW per year globally, and the IEA expects this to exceed 800 GW/year by 2030.
That is equivalent to adding one Hinkley Point C every 2–3 days in energy terms.
– Solar module prices fell over 90% in 15 years.
– Offshore wind is scaling into the 20–25 MW turbine era.
– Build times are 1–3 years, not 10–15.
Renewables (RES) are now the default new generation source worldwide, covering all the extra electricity demand in 2025.
Storage is scaling even faster than RES
Battery storage is the fastest‑growing energy technology on the planet.
– Global grid‑scale storage capacity doubled in 2023.
– Lithium‑iron‑phosphate (LFP) prices fell >50 percent in 2023 alone.
– Multi‑day storage (iron‑air, sodium‑ion, flow batteries) is entering commercial deployment.
– Pumped hydro is being expanded in Europe, China, and Australia.
By 2035, storage will be cheaper, more diverse (short, medium, long duration) and more widely deployed. LFP grid battery costs have fallen ~50 % in 2–3 years and the curve has not flattened yet. Battery storage cost projections are that they will be 60–75% cheaper in 10 years and probably >80% in 20 years.
This directly reduces the need for nuclear as a “firm” resource.
Demand follows supply
Demand‑side management is the emerging grid management tool.
Flexibility in demand is becoming a major grid resource and has been successfully pointed, and is not being operationalised. In fact NESO announced a nation wide introduction of ‘turn up’ and ‘turm down’ events, building on the saver sessions etc. from Octopus Energy, SSE and Eon. The electricity demand increases that could stress the grid are associated with the very technologies that can be controlled in this way:
– EV smart charging
– Heat pumps with thermal storage
– Industrial load shifting
– Data centre flexibility
– Home batteries and V2G
By 2035, many grids will have 10–20% flexible demand, which dramatically reduces the need for slow‑ramping baseload like nuclear.
Nuclear cannot scale fast enough
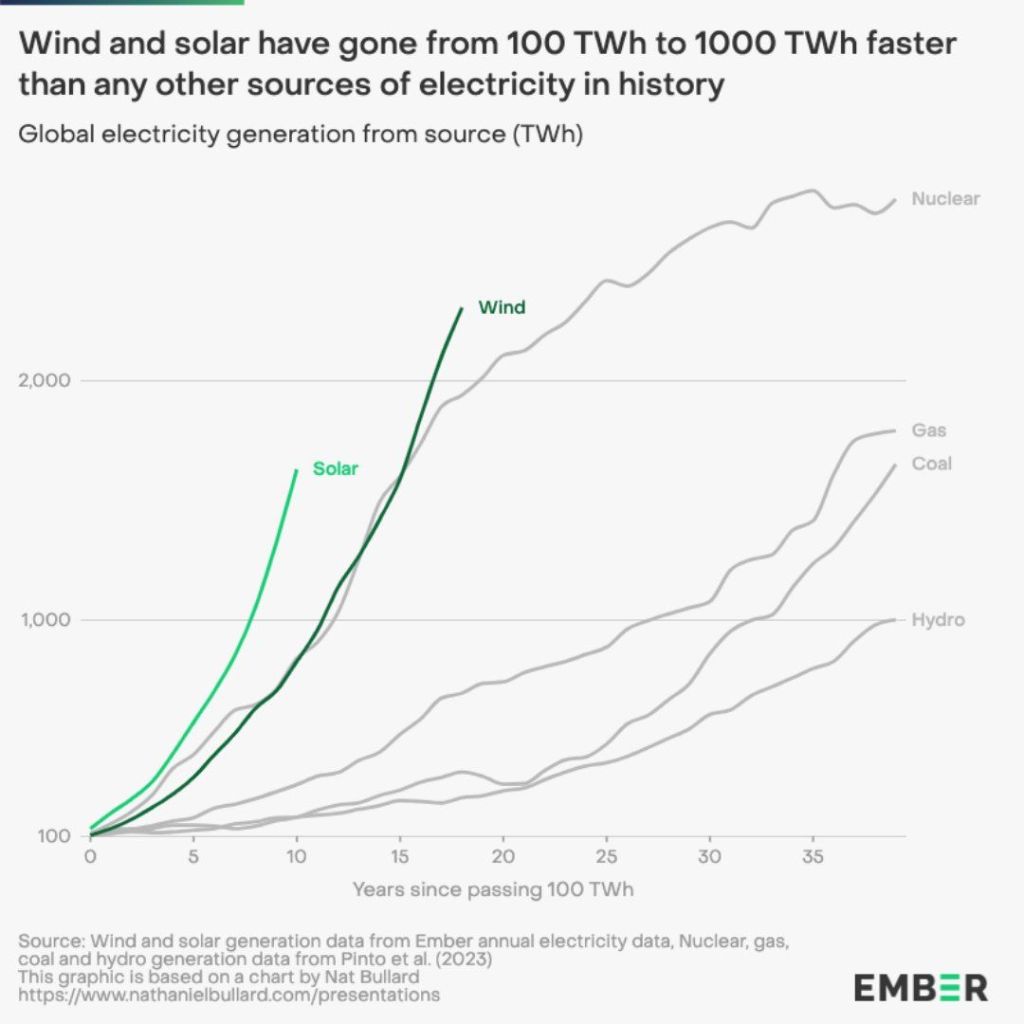
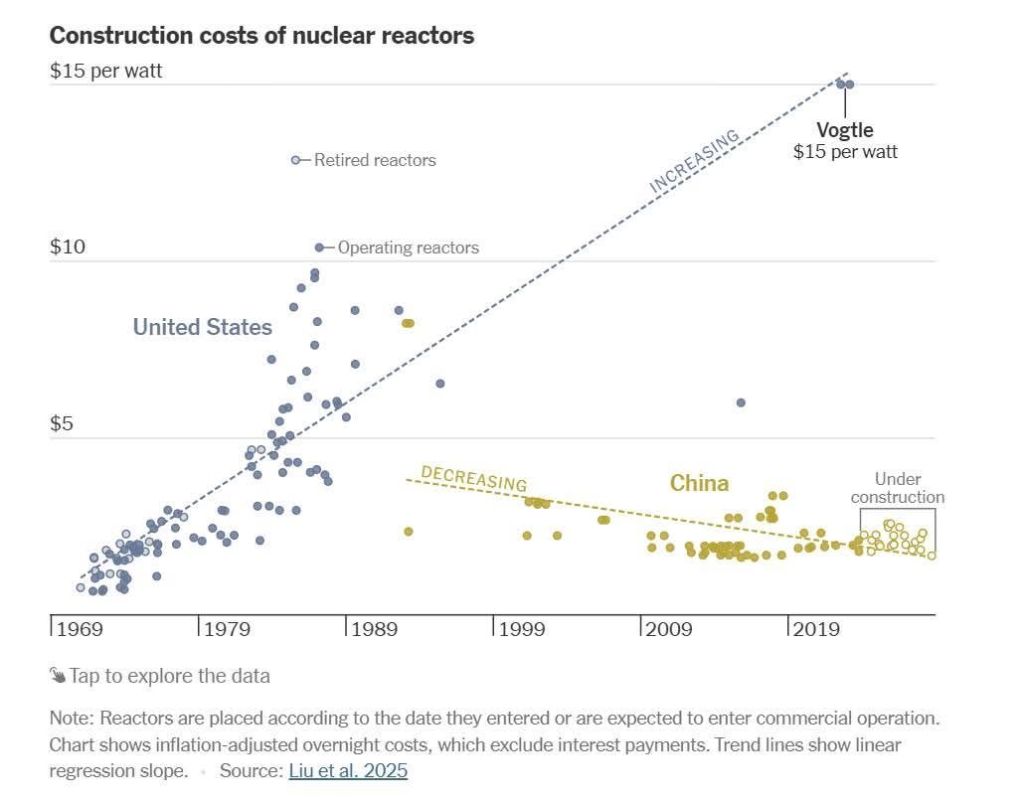
Even if you want nuclear, the timelines are incompatible with 2035–2045 decarbonisation goals. They can’t be built fast enough to matter in the medium term, even with massive capital spend.
SMRs may help, but there are only two production SMRs in the world. They are in Russia… SMRs are unlikely to play a major role where RES are an option.
Current nuclear plants:
– First concrete to operation: 10–15 years
– Cost overruns: common
– Workforce shortages: severe
– Supply chain constraints: chronic
– SMRs: effectively no commercial units operating yet; earliest realistic deployment is mid‑2030s, scaling in 2040s.
In contrast:
– A 1 GW solar farm can be built in 12–18 months
– A 1 GW offshore wind farm in 3–5 years
– A 1 GWh battery farm in 6–12 months
Nuclear simply cannot compete on deployment speed.
Economics
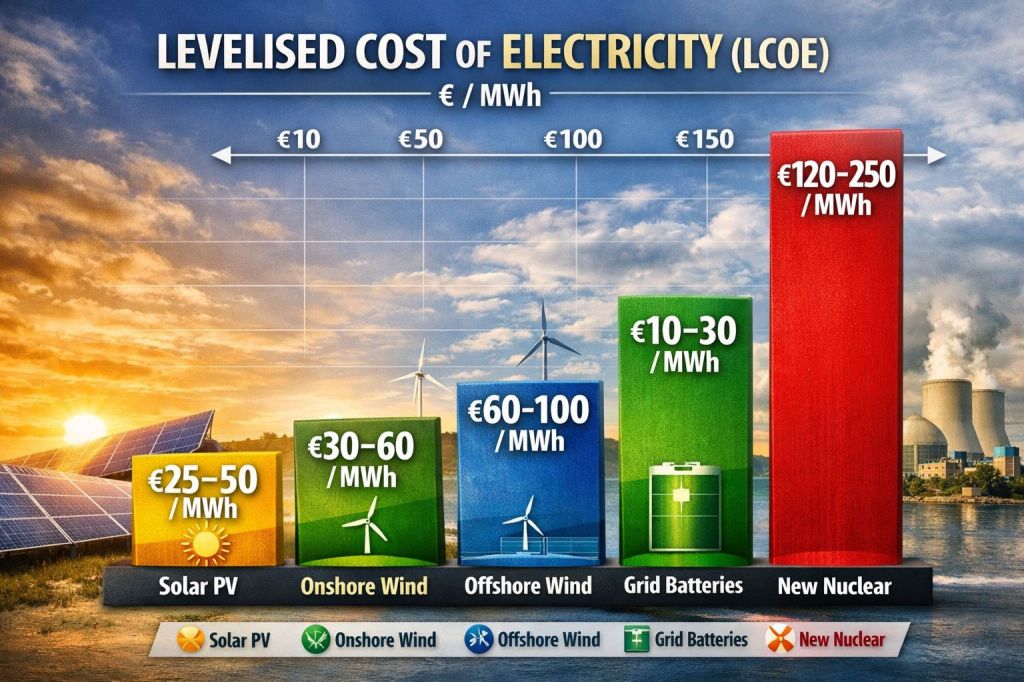
Nuclear is expensive. 3–5 times more expensive.
Levelised Cost of Electricity (LCOE) is a measure of the average cost to generate one megawatt‑hour of electricity over a power plant’s lifetime, including construction, operation, maintenance, and fuel, allowing direct comparison of technologies on a consistent £/MWh basis.
The Levelised Cost Of Electricity (LCOE) comparison is:
– Solar PV: €25–50/MWh
– Onshore wind: €30–60/MWh
– Offshore wind: €60–100/MWh
– Grid batteries: €10–30/MWh for shifting
– New nuclear: €120–250/MWh
This cost gap is widening, not narrowing.
Capital and costs
Given that a 100% renewables based grid seems technically possible maybe there is an economic argument in favour of nuclear. That comes down to cost to build plus cost to operate, giving a net cost per megawatt hour of electricity.
A modern 1.1 GW nuclear reactor produces ~8700 Mh/yr. Assuming demand‑side measures, interconnection and geographic diversity reduce long‑duration needs, then to produce that 8700 MWh/year from renewables would require a Renewables Energy System portfolio; for the UK mix it would probably be about:
1 GW nameplate capacity of offshore wind (50% capacity factor)
+ ~4.1 GW solar (11% capacity factor)
+ battery storage able to provide 1 GW output and 10 GWh storage (to cover daily and short multi‑day variability, not seasonal backup).
That mix would be provide for intermittency, with the frequent excess being exported via interconnects, or used for responsive industrial loads.
Capital expenditure
Using today’s costs:
Nuclear (1.1 GW): £6–10 billion
Vs.
– Offshore wind (1 GW): £2–3 billion
– Solar PV (4.1 GW): £2–3 billion
– Battery storage (1 GW / 10 GWh): £0.7–1.2 billion
Total RES + storage: £4.7–7.5 billion
Cost per MWh
Today’s cost per MWh (LCOE) for that amount of firm RES + storage would give a wholesale price of ~£53/MWh (£0.053 / kWh before grid and policy costs). Nuclear is at £100–210/MWh.
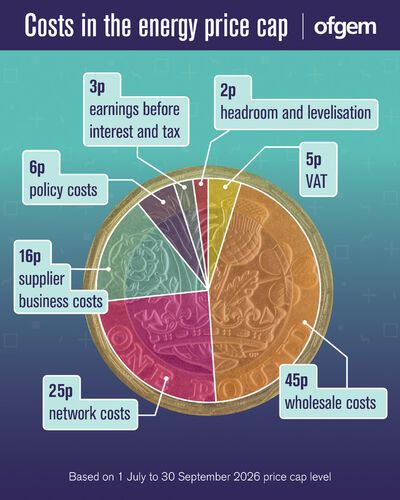
However, renewables technologies continue to get cheaper and better as they mature. With realistic learning curves, firm RES + storage falls to £36–£43 per MWh over the next ten years (by 2036) while even optimistic projections have nuclear at £94–£187 per MWh.
Nuclear electricity is at least double the equivalent renewables plus battery mix
By the time a nuclear reactor build started today is realistically operating, twenty years from now, we anticipate those numbers to be £77–£153 per MWh for nuclear while firm RES + storage is likely to be nearer £22–£32 per MWh.
Nuclear electricity is at least double the equivalent renewables plus battery mix now and, because it doesn’t become significantly cheaper over the coming decades, it will be 3 to 6 times more expensive by the time new generators come online in 20‑years.
UK scenario
A few facts and observations that underpin our prediction:
– Offshore wind pipeline growing to >100 GW
– The UK nuclear pipeline is mostly theoretical, Hinckley Point C is the only UK nuclear reactor under construction. Current cost is £48 billion (double the original budget) and will have taken 15 years to build.
– Grid scale storage is doubling every 2-3 years, currently at ~12.9 GWh and growing at 4GWh per year (-45%). There is 6.5 GW currently under construction and 60 GW+ consented in the pipeline. This is supplemented by ~200,000 home batteries providing a further 10+ GWh and 50% growth rates.
– Interconnectors provide two way electricity exchange with neighbouring countries. The UK has 9.8 GW interconnector capacity and a further 1.4 GW under construction.
Will we need grid‑connected nuclear in the next 10–20 years?
For most countries: no.
For some countries: maybe.
Countries unlikely to need nuclear
- UK
- Much of Europe, e.g.
- Denmark
- Spain
- Portugal
- Australia
- Chile
- Most of Africa
- Most of South America
Countries that may still want nuclear
- France (fleet replacement)
- Finland (political support)
- South Korea (industrial policy)
- Japan (energy security)
- China (all‑of‑the‑above)
- US (regional politics + existing fleet)
But even in these countries, nuclear is a policy choice, not a technical necessity.
In the medium term, RES + storage + demand flexibility will meet almost all new electricity needs in most regions. Nuclear is not required for grid stability or decarbonisation in that timeframe. Energy storage is very likely to have the capacity, longevity and cost-effectiveness to make nuclear a stranded asset. Unlike nuclear, the materials in batteries will be recyclable when they need replacing.
Nuclear may still be built for political, industrial, or strategic reasons, but not because the grid needs it.
 Sustainable Ferriby

2 responses to “Nuclear Power Vs. Renewables”
Excellent presentation of the argument and well researched. Interesting that people interested in the development of energy resources seem to be totally aware of the pragmatic solutions to future supply but those with the responsibility less so.
LikeLike
[…] the previous article there was a closing thought experiment section on ‘what if we stopped burning fossil fuels […]
LikeLike